For independent personal trainers in France
Independent personal trainer: the tool to run and grow your business
Being an independent personal trainer means doing two jobs: training your clients and running a small business. This page gathers the set-up checklist for France (qualification, professional card, legal status, insurance, invoices) with the 2026 figures and official sources, then shows how I Train With You brings your client follow-up and your documents together, from €0.
- The set-up checklist, backed by official sources
- The 2026 figures for micro-entrepreneurs
- A turnkey tool, with no commitment
Free for 1 client · no credit card · no commitment
Updated on 1 October 2026
The checklist to set up as an independent personal trainer in France
The steps below apply to a trainer coaching for pay in France as a micro-entrepreneur. Always check your own situation on the official sites listed at the bottom of the page (in French).
Hold a recognised qualification
The French Sports Code (article L212-1) reserves paid teaching, leading and coaching of a sport to holders of a diploma, title or qualification certificate that guarantees participant safety: BPJEPS, DEJEPS, a STAPS degree or a CQP depending on the discipline, each with its own conditions of practice. Working without a qualification is punishable by one year in prison and a €15,000 fine (article L212-8).
Declare your activity and get the professional card
Before you start, declare your activity as a sports educator (article L212-11) on the official declaration portal. You receive a professional card (carte professionnelle) to renew every five years. Your clients can check it on the public register of sports educators.
Choose your legal status
The micro-entreprise is the simplest status to start with: online registration on the one-stop business formalities site, contributions calculated on the turnover you collect, light bookkeeping. Coaching is in principle classed as non-commercial profits (BNC), as a non-regulated liberal profession; selling equipment or products falls under industrial and commercial profits (BIC).
Take out liability insurance
The French Sports Code (article L321-7) requires anyone running a physical activity business to be insured for civil liability, and an independent trainer organising their own sessions falls into that case. Check that the policy covers all your locations (client homes, outdoors, gym), your disciplines and online coaching if you do it.
Invoice with the right mentions
Each invoice shows, among other things, your name followed by "EI", your SIREN number, the date, a unique number, the details of the service and the price. Under the VAT exemption, add "TVA non applicable, art. 293 B du CGI". All businesses must be able to receive electronic invoices since 1 September 2026; micro-businesses will have to issue them from 1 September 2027.
Look into personal services (optional)
If you give one-to-one lessons at your clients' homes, you can declare a personal services (services à la personne) activity: in-home sports lessons are on the official list of activities. Your clients can then get, under conditions, a 50% tax credit, maintained for 2026. Sessions at a gym, outdoors or online do not qualify.
Put the relationship in writing
A quote or terms and conditions prevent most disputes: price, what packs include and how long they are valid, cancellation rules that are the same for you and the client, a health questionnaire. If you sell remotely to consumers, they usually have a 14-day withdrawal right.
The 2026 figures for a personal trainer micro-entrepreneur
Rates and thresholds published by the French administration for 2026, for a non-regulated liberal profession (the general case for personal training).
| Item | 2026 value | Good to know |
|---|---|---|
| Social contributions | 25.6% of turnover | Plus 0.2% for the vocational training contribution |
| Flat-rate income tax (option) | 2.2% of turnover | Replaces income tax, subject to a household income condition |
| Turnover ceiling | €83,600 per year | Services, thresholds valid for 2026 to 2028 |
| VAT exemption threshold | €37,500 (upper threshold €41,250) | Above the upper threshold, VAT is due from the day it is exceeded |
| Professional card | Valid for 5 years | Plan the renewal before it expires |
| Electronic invoicing | Receiving: 1 September 2026 | Issuing for micro-businesses: 1 September 2027 |
Sources (in French): service-public.gouv.fr for contributions, ceilings and the VAT exemption; impots.gouv.fr for electronic invoicing.
Example: from turnover to income
Take a trainer who bills 15 sessions a week at €50, over 44 working weeks. Annual turnover is €33,000, below the VAT exemption threshold. Social contributions come to €8,448 (25.6%) and the vocational training contribution to €66. That leaves €24,486 before real expenses (insurance, travel, equipment, phone, software) and before income tax.
Two lessons: billable hours are the real ceiling on income, and every hour lost to admin or travel costs you. Our guide on pricing your coaching services helps you set a price that accounts for these costs.
What I Train With You brings together for you
I Train With You is a turnkey tool: client management and your professional profile in one place, without paying for several pieces of software.
Your legal profile and documents
SIREN and SIRET checked on entry, VAT regime, personal services number, professional card, diploma and insurance certificate stored in a private space. You are reminded 30 days and then 7 days before each expiry date.
Client follow-up
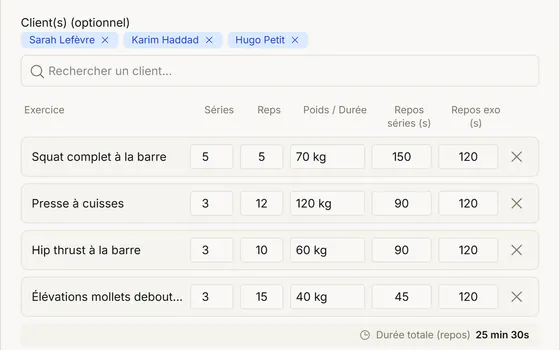
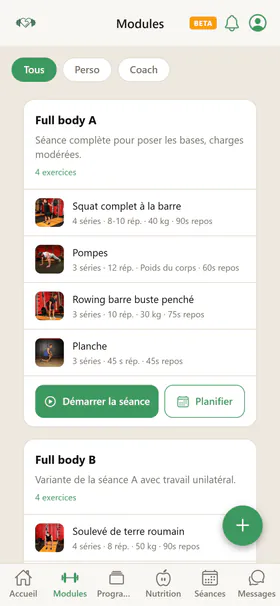
Client profiles, training programs, meals calculated with the French CIQUAL food table, completed sessions and ratings: everything behind the quality of your coaching. Details on the personal trainer software page.
Calendar and cancellations
Availability, bookings, automatic reminders and a late-cancellation rule that is the same for you and your clients. See personal trainer scheduling.
Professional messaging
Your conversations with each client, kept apart from your personal messages, with photo and PDF attachments.
- Coming soon
Invoices, payments and contracts
Compliant invoices, online payment and contract templates are on the way. Your legal profile is already ready for them.
No lock-in
You keep your clients, your prices and your way of invoicing. No exclusivity, no commitment, and you can ask for an export of your data at any time.
Grow your business without depending on a platform
An independent trainer gains freedom but loses any guaranteed flow of clients. The answer is not to hand everything to a platform that takes a commission on every session, but to build channels you control: your network, a Google profile, health professionals, companies, reviews. Our guide on how to get personal training clients covers 12 methods.
On the admin side, remember that admin time is never billed. A tool that sends reminders, keeps each client's history and warns you before your documents expire gives you hours back every month. For more on organisation, read running an independent fitness coaching business.
How much does I Train With You cost an independent trainer?
Every plan has the same features: only the quotas change (clients, custom exercises, meals, modules). You start for free with a real client, then move to Starter (€3.90 per month excl. VAT) or Pro (€10.90 per month excl. VAT) as your business grows.
Free
€0excl. VAT / month
Free, no credit card
1 client
Starter
€3.90excl. VAT / month
€4.68 incl. VAT
3 clients
Pro
€10.90excl. VAT / month
€13.08 incl. VAT
10 clients
Elite
€49.90excl. VAT / month
€59.88 incl. VAT
Unlimited clients
Prices exclude VAT, with no commitment and no credit card for the free plan. Compare the plans in detail.
Coming soon, as a bonus: requests from nearby clients
Coming soonI Train With You is preparing a matching service: people will post a request (goal, area, availability) and verified coaches in the area will be able to answer with their rate. It will open city by city, with no promise of volume. It is an extra: the management tool is already complete without it. To hear about the opening, subscribe to the newsletter at the bottom of the page.
Frequently asked questions
Which legal status should an independent personal trainer choose?
In France, the micro-entreprise suits most beginnings: online formalities, contributions proportional to the turnover you collect, no contributions without turnover. Above €83,600 of annual turnover, or if your real expenses are high, an individual business on the real regime or a company can become more attractive: ask a chartered accountant.
Personal trainer in France: BIC or BNC?
Coaching services are in principle classed as BNC, as a non-regulated liberal profession, with 25.6% social contributions in 2026 as a micro-entrepreneur. If you also sell equipment or products, that part of the business falls under BIC.
Is the professional card mandatory?
Yes, for any sports educator working for pay in France. You get it by declaring your activity online, and it must be renewed every five years. The public register lets anyone check that a trainer is declared.
What insurance does an independent personal trainer need?
Professional civil liability insurance is mandatory. Choose a policy that covers your disciplines and all your locations, and consider cover for your own accidents, since an independent is not covered like an employee.
Freelance or independent personal trainer: what is the difference?
None in legal terms: "freelance" is simply another word for self-employed. A freelance trainer works on their own account, usually as a micro-entrepreneur, with the same qualification, professional card and insurance obligations.
Does an independent personal trainer have to charge VAT?
Not while turnover stays below the VAT exemption threshold (€37,500 in 2026 for services, with an upper threshold of €41,250). Invoices then carry the mention "TVA non applicable, art. 293 B du CGI".
How much does an independent personal trainer earn?
There is no single figure: income depends on the session price, the number of billed hours and expenses. For €33,000 of turnover as a micro-entrepreneur, about €24,500 remains after contributions, before real expenses and income tax. The main lever is how full your calendar is.
Further reading
- PageGetting clients12 practical ways to get personal training clients when you work independently: your network, a Google profile, reviews, partnerships, content, referrals.
- PagePersonal trainer softwareClients, programs, nutrition, scheduling and messaging in one personal trainer software. Free for 1 client, no credit card, no commitment, no lock-in.
- PagePricingFree, Starter €3.90, Pro €10.90, Elite €49.90 per month excl. VAT. Free for 1 client, no credit card, no commitment and no lock-in.
- GuideHow to Retain Clients as a Fitness CoachA client who stays makes more progress, recommends you and keeps your schedule predictable. Goals, visible progress, clear rules and renewals: a practical retention method.
- GuideHow to Price Your Personal Training Services: The Calculation MethodTarget income, contributions, expenses and truly billable hours: a step-by-step method to calculate your minimum rate as an independent personal trainer in France, then build sessions, packs and subscriptions.
- GuideClient Onboarding in Fitness Coaching: Turning the Trial into CommitmentThe first two weeks with a new client are decisive. Welcome interview, intake questionnaire, first sessions, welcome kit: how to structure onboarding to build commitment.
Official sources
Information checked against these sources on the update date shown.
- Service-public: micro-entrepreneur social contributions
- Service-public: micro-entreprise turnover ceilings
- Service-public: VAT exemption threshold
- Impots.gouv.fr: electronic invoicing
- Sports educator declaration portal
- Public register of sports educators
- Landes prefecture: professional card for sports educators
- Légifrance: French Sports Code, article L321-7 (insurance)
- Personal services: the 26 activities